


Gold Bull Market Not Over, Fidelity International Bullish on 2027 Recovery
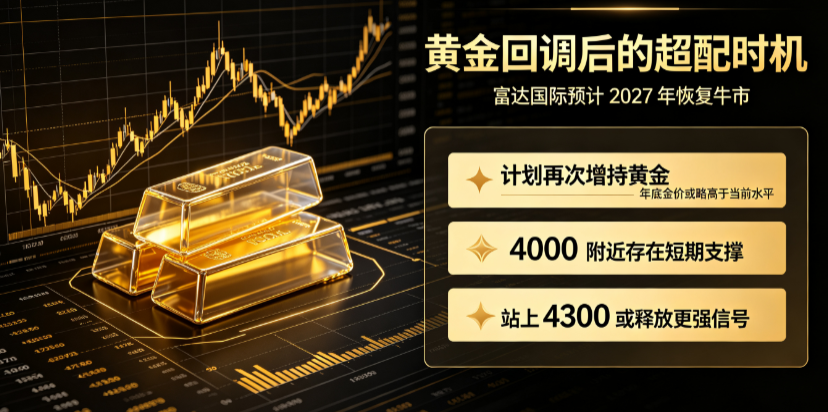
Fidelity International holds a contrarian bullish view on gold, viewing the 2026 correction as a positioning opportunity with the bull market resuming in 2027. The core logic supporting gold's long-term trend remains unchanged, advising investors to shift from neutral to overweight.
Gold Bull Market Not Over: Fidelity International Contrarian Bullish on 2027 Recovery Path
Keywords
Gold price, Fidelity International, Asset allocation, Bull market, Inflation expectations, Geopolitics, Technical analysis, Central bank policy
Introduction: Deep Logic Behind Gold Price Correction
Early 2026 saw global financial markets in turmoil. Gold, the safe-haven asset that narrowly missed a $5,600 record high earlier this year, plunged under the shock of the Iran war, recording its worst quarterly performance in over a decade. As market sentiment shifted from euphoria to panic, many investors began questioning whether gold's long-term bull market had ended.
Yet amid the noise and pessimism, Ian Samson, portfolio manager at renowned asset management firm Fidelity International, struck a different note. He believes the core logic supporting gold's long-term trajectory remains intact, and a true bull market will restart in 2027. He sends a clear signal to investors: now is the optimal time to shift from "neutral" to "overweight" gold.
1. From Historic High to Deep Drop: What Does Gold's Correction Mean?
In late January 2026, gold began retreating from near its all-time high of $5,600 per ounce. Just one month later, with the outbreak of the Iran war, geopolitical risks escalated sharply, accelerating gold's decline in both depth and speed, catching many investors accustomed to gold's "safe-haven halo" off guard.
This correction was not an isolated event. Under the combined pressure of an increasingly complex global macroeconomic environment, aggressive tightening by central banks, and a strengthening US dollar, the gold market faced immense headwinds. However, Samson clearly stated in a recent interview: "The key trends that drove gold to its historic high of $5,600 per ounce earlier this year remain in place." This means that even after such a brutal drop, gold's long-term bullish logic has not been broken.
So what forces once pushed gold to its historic peak? The answer lies in three core variables: persistently high global inflation, uncertainty over major central bank monetary policy shifts, and a systemic rise in geopolitical risks. These three factors intertwine to create a macro "greenhouse" highly favorable to gold.
2. Fidelity International's Position Adjustment: The Overweight Window Is Opening
Samson revealed a telling detail: between January and February 2026, he downgraded his gold holdings rating from "overweight" to "neutral." The timing of this move—just before gold fell from its $5,600 high—showed his team's keen grasp of short-term market rhythm.
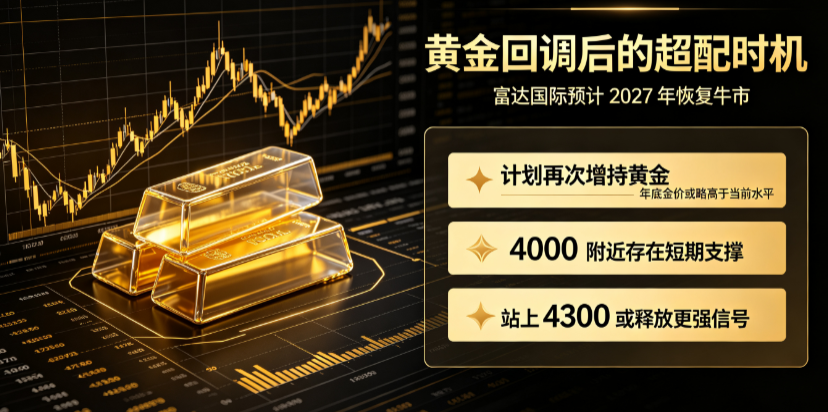
But now, after gold's deep correction, Samson has done a 180-degree turn. He explicitly stated: "We plan to overweight gold again. The question now is when to act." This signals that Fidelity International believes current gold prices already reflect market pessimism, and may even be oversold.
In asset allocation, switching between "overweight" and "neutral" often represents a major judgment by an institution on an asset class's future relative return. Samson believes gold allocation in investor portfolios should shift from "neutral" to "overweight." The logic: in the current macro environment, gold not only hedges tail risks but also has the potential to generate excess returns during a future recovery.
3. 2027: Fidelity International's Timetable for Bull Market Restart
Samson's long-term confidence in gold is not based on betting on short-term price rebounds. He provides a clear timetable: "The firm expects gold to re-enter a bull market sometime in 2027." This indicates Fidelity does not anticipate an immediate resumption of the prior uptrend. In fact, Samson admits: "From a strategic perspective, bullish and bearish factors are equally present. I expect gold prices to be slightly above current levels by year-end."
From a professional investor's view, the market often needs a time window to move from "deep decline" to "repair" and then to "recovery." The remainder of 2026 may be a period for gold to bottom out and build momentum; 2027, as the global economy enters the next policy cycle and geopolitical risks dissipate, will be a critical point for gold to regain upward momentum.
This forward-looking judgment is based on Fidelity International's deep understanding of the global macro environment. Samson notes that unless there is a fundamental shift, "unless governments return to orthodox fiscal policies and central banks truly strive to lower inflation, the bullish case for gold remains intact. But I don't think that's the world we're in right now."
4. Three Key Variables Determining Gold's Fate
Whether gold can launch a new bull market in 2027 as expected depends on several key variables. Samson believes investors should closely monitor the following three points:
First, the future trajectory of oil prices. As the "blood" of the global economy, oil price fluctuations directly impact inflation expectations and central bank policies. If oil prices rise persistently due to geopolitical conflict, they will exacerbate global inflation pressures, providing gold with both safe-haven and inflation-hedging support. Conversely, a sharp drop in oil prices could ease inflation and weaken gold's appeal.
Second, the Fed's interest rate policy. The pace and magnitude of the Federal Reserve's rate hikes are core drivers of gold prices. Historically, gold has a negative correlation with real US interest rates. If the Fed maintains high rates or hikes further, it will pressure gold; if it starts cutting rates or signals easing, gold will see a strong rebound.
Third, the technical picture of the gold market itself. Repair of market sentiment and improvement in technical indicators are necessary for a gold price recovery. Samson notes from a technical analysis perspective that the first bullish signal would be the 50-day moving average crossing above the long-term moving average, or gold rising back above $4,300 per ounce. This would confirm an upward trend from a technical standpoint.
From a technical perspective, Samson believes gold may find support near $4,000 per ounce in the near term. This price level has been tested and supported multiple times in past years, carrying significant psychological and technical importance. If gold can hold this level and gradually form a bottom structure, it will lay a solid foundation for the 2027 bull market.
5. Geopolitical Risk and Inflation: Gold's "Twin Engines"
Gold is deemed the "ultimate safe-haven asset" because it preserves value during extreme risk events. The Iran war is the latest validation of this logic. Although the shock triggered a short-term gold crash (due to liquidity crisis and margin pressure), in the long run, wars often fuel inflation expectations, undermine fiscal discipline, and weaken fiat currency credibility, ultimately benefiting gold.
Samson takes a broader view: he focuses not just on a single geopolitical event, but on the possibility of "governments returning to orthodox fiscal policies." In reality, many countries are burdened with high debt and large fiscal deficits, and central banks face immense political pressure. In such an environment, truly thorough fiscal and monetary tightening is nearly impossible. As long as this "unorthodox" state persists, the bullish case for gold remains valid.
Inflation is the other major driver. During 2024-2025, the world experienced historic inflation; despite aggressive rate hikes by central banks, core inflation remained elevated. When inflation expectations become entrenched, real assets and inflation-hedging assets gain favor. Gold, as a natural "inflation hedge," has historical data amply demonstrating its performance during inflationary periods.
6. Investor Strategy: How to Seize the 2027 Gold Rally?
Based on Fidelity International's assessment, how should investors position themselves in gold now? Here are several specific suggestions:
(1) Adjust allocation ratios, shift to "overweight." For investors on the sidelines, now may be a good opportunity to gradually build positions. Don't try to perfectly time the bottom; instead, buy in tranches within the bottoming range to lower average costs. Samson's emphasis on shifting from "neutral" to "overweight" highlights the strategic importance of allocation weight.
(2) Monitor technical signals, wait for confirmation. Technical analysis can help investors identify optimal entry points. Watch whether gold can effectively break above $4,300 and whether short-term moving averages form a golden cross. When these signals appear, they often indicate a fundamental shift in market sentiment.
(3) Combine macroeconomic data, adjust dynamically. Closely track core indicators such as oil prices, US CPI data, and Fed meeting minutes. If these move in gold's favor, increase positions appropriately; otherwise, manage risk.
(4) Maintain a long-term perspective, avoid chasing rallies and selling into dips. A long-term gold bull market won't happen overnight; fluctuations are inevitable. Samson's timetable points to 2027, meaning gold may remain in a choppy bottoming process over the next six to twelve months. Investors need patience to avoid deviating from long-term strategy due to short-term volatility.
Conclusion: Gold's "Halftime Break," Not the End
When gold prices plummet from $5,600 highs and market sentiment swings from euphoria to despair, it's natural to wonder: Is the gold bull market over? Fidelity International's answer is no; this is just a "halftime break."
The deep structural forces driving gold higher—global inflation, geopolitical conflict, fiscal expansion, and central bank policy swings—have not disappeared; in some ways, they are intensifying. When these forces reconverge in 2027, gold is poised to return to center stage and launch a new rally cycle.
For rational investors, now is not a time to be dominated by panic, but a critical window for calm analysis and strategic positioning. As Samson said: "We plan to overweight gold again. The question now is when to act." That "when" may be now.
Gold, an asset with a long history, is telling us in its own way: The end of a bear market is often the starting point of the next bull market. And 2027 may be the time for this "golden star" to shine again.
All information, quotes, analysis, and research reports on this website are for reference only and do not constitute any investment advice, trading recommendations, or financial solicitation. Market risk exists, invest with caution.