


Gold-Silver Ratio Breaks 100: Warning of Silver Industrial Demand Collapse, Precious Metals Safe-Haven Logic Fully Differentiates
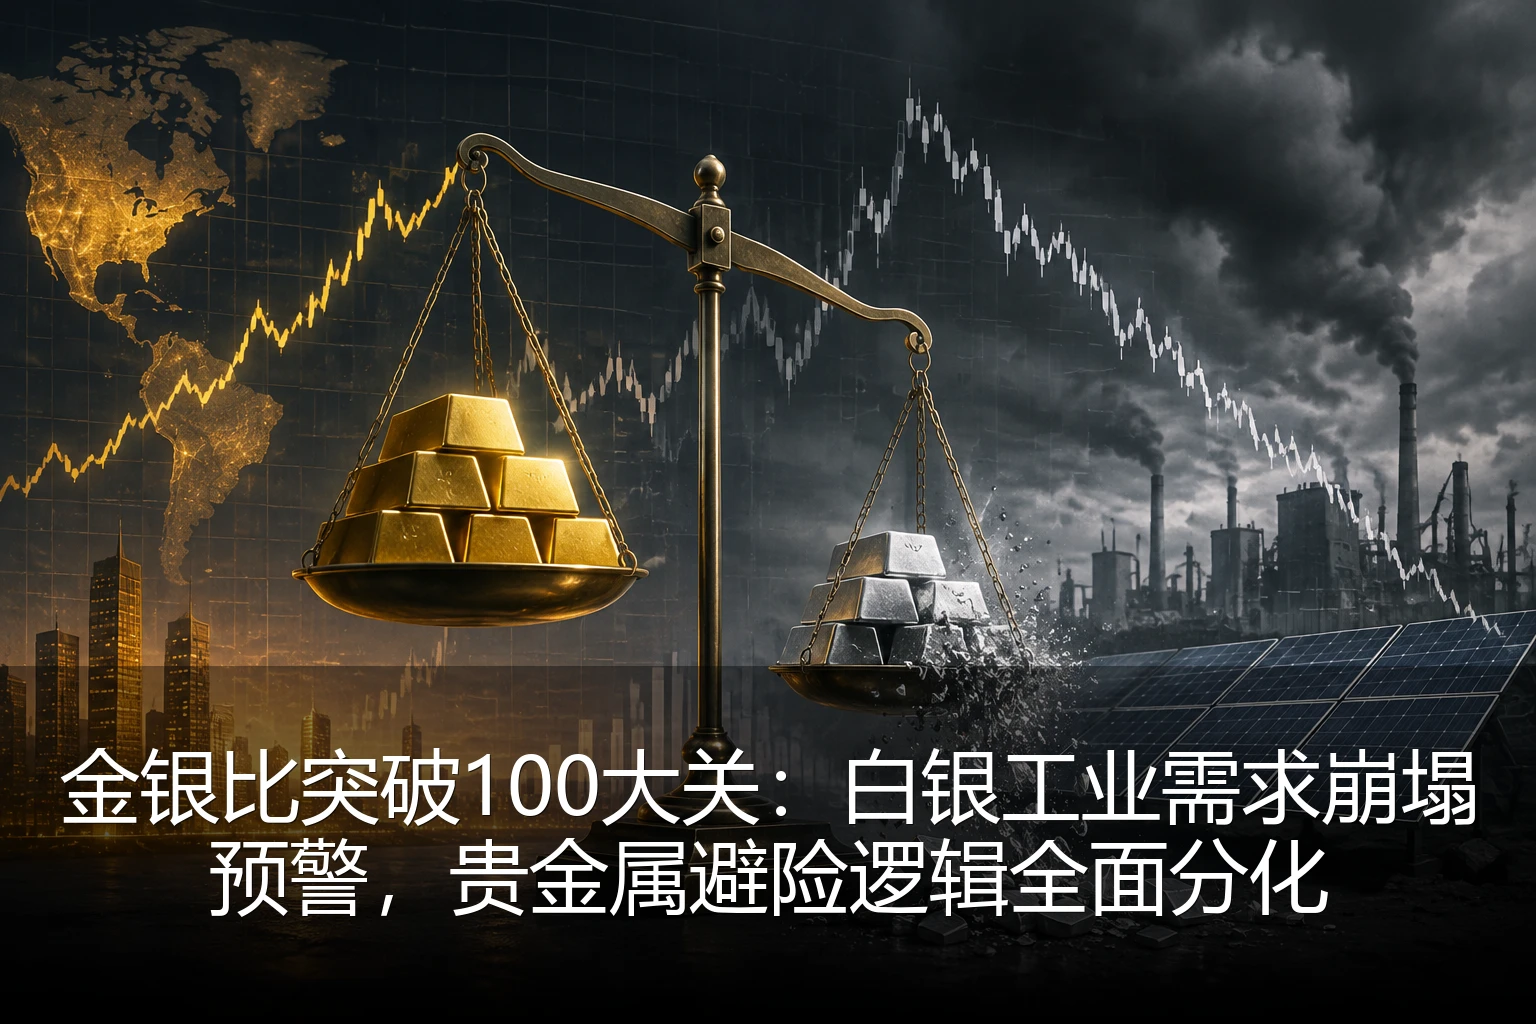
On August 3, 2026, the international precious metals market showed key differentiation, with the gold-silver ratio breaking the 100 mark again after two years. Against the backdrop of escalating global trade friction and increasing concerns about manufacturing recession, gold as a safe-haven asset oscillated at high levels, while silver was dragged down significantly by expectations of industrial demand collapse. This article deeply analyzes the economic recession signals behind the surge in the
Market Shows Extreme Trend: Safe-Haven and Industrial Attributes Greatly Differentiate
During the just-passed weekend, global trade tensions suddenly escalated, combined with the latest manufacturing data all missing expectations, on August 3, 2026 Asian morning, the precious metals market presented an extremely rare "icy and hot" pattern. International spot gold, supported by safe-haven funds, remained above $4150/oz oscillating at high levels, while international spot silver suffered heavy losses, once falling below the $42/oz mark intraday. Between this rise and fall, the Gold/Silver Ratio, which measures how many ounces of silver one ounce of gold can buy, surged sharply, breaking through the 100 mark in Asian trading hours, reaching a high of 101.5, the highest level since mid-2024.
At the time of publication, London spot gold was quoted at $4165.80/oz, up 0.4% for the day; while London spot silver was quoted at $41.45/oz, down as much as 3.2% for the day. This sharp divergence completely broke the market's inherent perception of "precious metals bull market rising together," marking a shift in market logic from simple monetary easing expectations to deep concerns about real economic recession.
Gold-Silver Ratio Breaks 100: Leading Indicator of Recession Trading
The gold-silver ratio has always been regarded as the "thermometer" of macroeconomic health. When this ratio rises, it usually indicates strong market risk aversion and pessimism about economic growth prospects. Gold, as a purely monetary asset and ultimate safe-haven tool, continues to benefit from geopolitical turmoil and currency depreciation expectations; while silver, with over 50% industrial attributes (covering photovoltaics, electronics, medical fields, etc.), its price is often closely linked to the global industrial cycle.
The gold-silver ratio breaking 100 this time was mainly triggered by the global major economies' July manufacturing PMI data released last weekend. The data showed that the US ISM manufacturing PMI unexpectedly fell to 46.8, in the contraction zone for the fourth consecutive month; the Eurozone manufacturing PMI final value was even more dismal at 44.1. More critically, the intensifying global trade friction is escalating from the tariff level to technical blockade, with market concerns that global semiconductor and new energy industry chains will face unprecedented shocks. Against this background, silver's role as the "industrial vitamin" is being re-priced, and investors began to panic sell silver long positions, turning to gold for shelter.
Silver Industrial Demand Warning: Photovoltaic Silver Faces Cliff Risk
In the industrial demand structure for silver, the photovoltaic industry has been the largest growth engine in recent years. In 2025, global photovoltaic silver consumption reached a record 6,500 tons, accounting for nearly 30% of total industrial demand. However, as multiple countries begin to cut new energy subsidies, and trade friction has led to obstacles in key component imports and exports, the third quarter 2026 photovoltaic installation volume has been significantly downward revised.
An industry research report released on August 2 pointed out that the world's largest photovoltaic market, due to grid consumption capacity saturation, is planning to implement stricter grid connection reviews for new distributed photovoltaic projects in the fourth quarter. This means that the previously extremely overdrawn silver industrial demand expectations are reversing. Once the growth rate of photovoltaic silver usage drops sharply from the expected 15% to single digits or even negative growth, the silver market will face serious supply-demand imbalance. This multi-empty game driven by both "safe-haven logic" and "industrial recession logic" makes silver one of the most vulnerable assets in the current macro environment.
Why Gold Alone Thrives? Safe-Haven Buying and Central Bank Actions
In stark contrast to silver's dismal performance, gold prices have shown strong resilience after breaking $4000. In addition to geopolitical risk premiums, the market is pricing in possible emergency rate cuts by the Federal Reserve in September. The bond market yield curve inversion has intensified, and expectations of declining real interest rates provide solid bottom support for gold. Meanwhile, although the July central bank gold purchase data has not been released yet, tracking shows that several emerging market central banks made significant purchases when gold prices fell back to the $3900 range, which greatly limited gold's downside space.
From a technical perspective, gold has built a solid support platform around $4100, with the MACD indicator showing a golden cross and upward momentum still abundant. Silver, after breaking the key support level of $45, has turned to a bearish technical pattern, with the next important support level directly looking at the $40 integer mark. If the gold-silver ratio continues to operate above 100, this will be an extreme signal rarely seen since the 1990s, meaning the market is pricing in a deep global economic recession.
Outlook and Investment Warning
In the current extreme market conditions, the risk of holding silver long positions has急剧放大. Investors need to closely follow the US July non-farm employment data to be released this week. If the job market weakens simultaneously, it will further confirm recession concerns, at which time gold may benefit from stronger rate cut expectations to continue its upward push, while silver may face a second round of selling due to demand collapse expectations, and the gold-silver ratio may even challenge the historical extreme area of 110.
For precious metals investors, the current trading logic should shift to "going long on gold for hedging, avoiding pure silver longs." After the gold-silver ratio broke through 100, some hedge funds have begun to execute "gold long, silver short" arbitrage strategies. For ordinary investors, physical gold bars and gold ETFs remain the core of defensive asset allocation in the third quarter of 2026. For silver, although prices have fallen significantly, it is not advisable to blindly bottom fish before the industrial demand inflection point is confirmed; it is more prudent to wait for photovoltaic industry policies to clarify before making a right-side layout.
All information, quotes, analysis, and research reports on this website are for reference only and do not constitute any investment advice, trading recommendations, or financial solicitation. Market risk exists, invest with caution.